Fixed before the first run.
Every published limit is checked on the loan the moment it is dropped, before DU or LPA sees it. Where one is broken, the change that clears it without breaking another is made in the loan.
Every limit, before the first run.
Today the rework starts after DU says no, one finding at a time. Proxara starts when the loan is dropped: the numbers in the loan file, the income it has calculated, the ratios worked out from both, and every limit the guides and the investor publish.
What only the AUS can decide stays with it. A risk-based Refer comes from a model the agencies keep to themselves; everything they publish is met before the file goes in.
The loan answers its own questions.
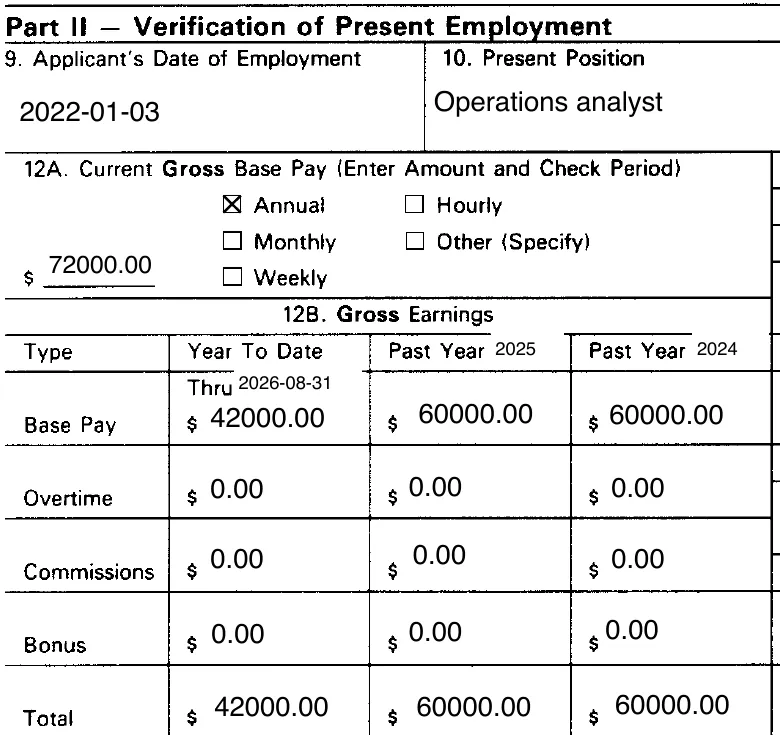
Type the loan number, and what the page needs before it can read (DU, LPA or FHA, which income counts, when the job started, the application and closing dates) fills itself in from the loan, for the officer to confirm.
Then the documents are held against the application: the employer on the paystub, the start date on the verification, the income on the W-2. Where they disagree, the page says so now, not when the lender’s underwriter finds it.
One change that clears every limit.
A fix that clears one limit can break another, and the next run finds it. Proxara combines the moves, checks every combination against every rule, and ranks the ones that clear them all by the borrower’s cash, the payment and how little has to change. The borrower chooses.
The exact value for every move.
Where the guide publishes the number (a debt-to-income, loan-to-value, loan amount or reserve limit), Proxara works out the exact value each move needs to clear it, and the structure carries that value.
DU and LPA do not publish a passing number for every decision. There Proxara works out the legitimate moves still open and puts the strongest first, instead of pretending a threshold exists.
Proxara never imitates DU or LPA. It submits the loan to the real AUS and works what comes back within seconds, so the next round starts at once.
Fannie Mae, Freddie Mac and FHA, fetched and diffed on a schedule
Where next
Bring the file that took the most runs.
Book a call and we take it from the first document to approval.